Commercial loans, structured around the business.
Lenders read a business differently from a wage. We prepare the application the way they assess it.
The anatomy of
a commercial deal.
Four things every lender reads, each weighed differently across our panel.
-
Who borrows,
Entity
You, a company or a trust. Each changes the guarantees and documents.
-
what secures it,
Security
Property, business assets or none. Unsecured usually means different pricing and lower limits.
-
what repays it,
Cash flow
The financials, the cash cycle and any seasonality.
-
how long it runs.
Term
Deposits are usually larger and loan terms shorter than for residential lending.
What lenders look at, by loan type.
| Commercial property | Business loans | Buying a business or franchise | |
|---|---|---|---|
| Read first | The property type, the lease and the tenant | The financials, the cash cycle and any seasonality | The business's trading history and the sale contract |
| Money in | The rent against the loan | How and when the business is paid | How the business has traded |
| Security | The property itself | Property, business assets, or none (unsecured) | Goodwill, stock, equipment, sometimes the premises |
| You | The borrower's own finances | Any personal guarantees a lender would ask for | Your experience in the industry and how much you are contributing |
| Run the numbers | Estimate commercial loan repayments | Estimate business loan repayments | Estimate repayments on a business purchase |
| More detail | Premises, investments and refinancingDeposits are usually larger and terms shorter than for a home.
| Facilities, fees and guaranteesWe set out the facilities that match, with the fees, the security and any personal guarantees.
| Franchise systemsSome lenders accredit franchise systems. We check whether yours is on a lender's list and work alongside your accountant and solicitor. |
The deal timeline, to settlement.
We plan around your dates and tell you where it is at every stage.
- Step 1
A first conversation
The business, the purchase and the timing.
- Step 2
Your options, set out
Lenders, structures, fees and security, subject to lender criteria.
- Step 3
A recommendation, with reasons
In writing, with the cost and what is secured.
- Step 4
Settle, and stay in touch
We run it to settlement, and stay for the next one.
Documents for a business deal
We confirm the exact list before anything is lodged.
Documents you will need
For every application
- Photo ID
- Verified in person, by video or electronically, as our privacy policy describes.
- Tax returns and financial statements
- Usually two years, personal and business, plus your latest BAS.
- If those are not ready
- Some lenders accept alternatives, usually with different pricing and a larger deposit.
For a property or a purchase
- Leases and contracts
- Financials, forecasts, leases and contracts.
- The sale contract
- With the trading history and your contribution.
Commercial and business lending
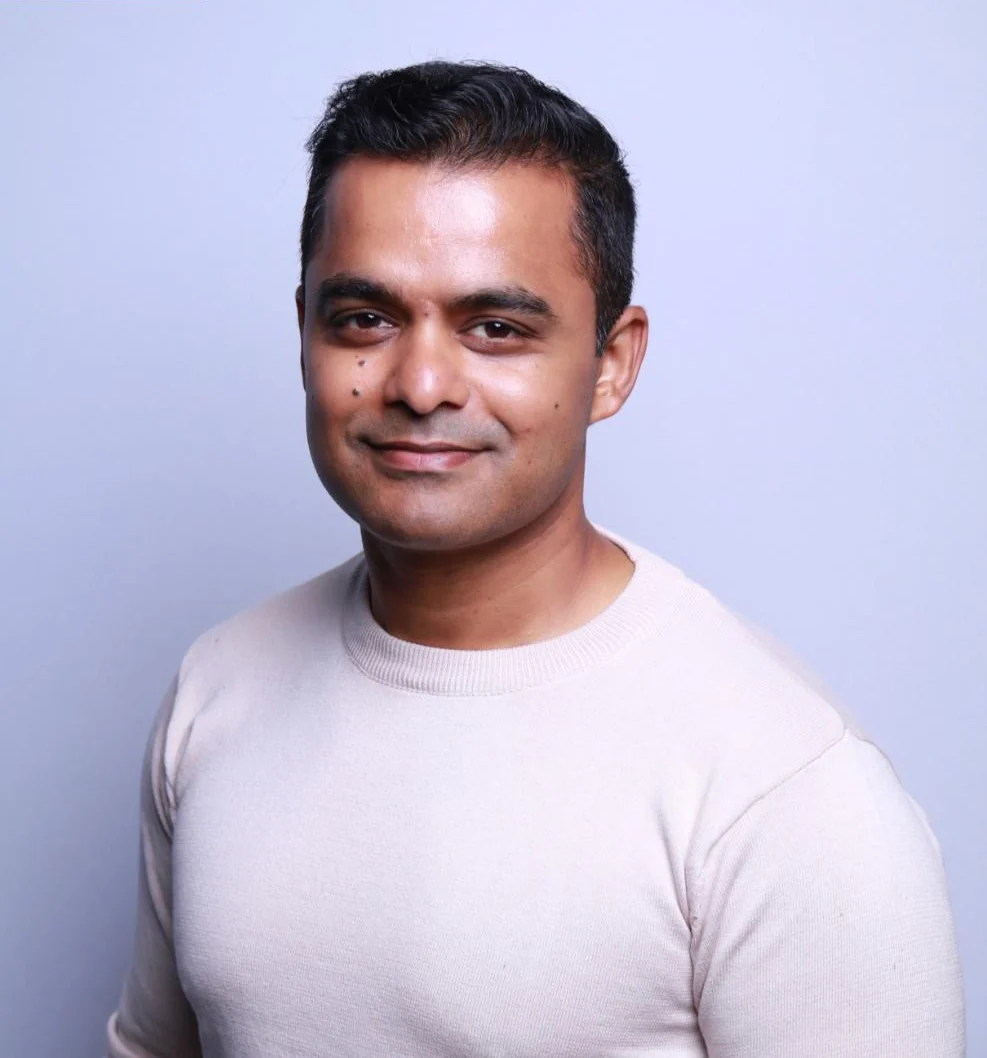
Eldo Jacob
Founder and property finance strategist
Commercial property, business loans and business purchases, with the security and the costs explained.
He structures complex loans and deals, including company structures, trusts and SMSFs.
- Phone
- (03) 4224 0732
- Office
- Suite 2, 23-31 Gheringhap Street, Geelong VIC 3220
Eldo Jacob is a credit representative (505957) of Buyers Choice Licencing Pty Ltd, Australian Credit Licence 509484.
Questions about business lending.
Do I pay anything to use a mortgage broker?
For most home loans, no. The lender pays us a commission when your loan settles, and often a smaller ongoing commission while it runs. A fee may apply for loans through a trust, commercial lending or more complex transactions. If a fee applies to you, we tell you the amount in writing before you go ahead, and our credit guide sets out how we are paid. Fees are more common in commercial and business lending than in home loans.
Do I need a deposit for a commercial property?
Usually, and often a larger one than for a home. The amount depends on the lender, the property type, the lease and the security offered. We set out what applies to your purchase, subject to lender criteria.
Can I use my home as security for a business loan?
Often you can, and many business loans are secured this way. It puts your home at risk if the business cannot repay, so we explain exactly what is being secured before you decide, and we recommend you get your own legal advice before signing.
Can I get a business loan if the business is new?
Some lenders on our panel will consider a business with a short trading history, often with more security, a larger contribution or evidence of your experience in the industry. We tell you which lenders fit and what they would ask for.
Which entity should borrow: me, my company or my trust?
It depends on your structure and your accountant's advice. Each option affects the guarantees, the documents and how the loan is assessed. We work through it with your accountant before an application is lodged.
Business-purpose lending sits outside the consumer credit laws that govern home loans. We work the same way regardless: the costs, the security and our reasons are set out in writing before you decide.
General information only. It does not take into account your objectives, financial situation or needs. Any figures are estimates only, subject to lender criteria, credit assessment and a full needs analysis. Not a credit offer.
Bring the deal to Eldo.
Settlements, lease starts and business handovers have dates. We plan the application around them.